
On this page
An energy supplier is responsible for providing energy to homes and businesses, and for almost every household in the UK that relationship is unavoidable in some form1. But it is narrower than it was a decade ago, and it can be made narrower still. Solar panels, batteries, heat pumps and schemes that reward shifting when you use electricity all reduce what a household buys from a supplier, and in the case of export, can turn the relationship into one where the supplier pays you.
What independence does not mean is leaving the grid. The Feed-in Tariffs scheme, which paid hundreds of thousands of homes for generating their own electricity, closed to new applications from 1 April 2019, and all pathways for accreditation are now closed2. Export payments today run through licensed suppliers, standing charges remain for the network connection, and the UK as a whole still met 75.2% of its energy consumption from fossil fuels in 20243. The realistic goal is a smaller, more deliberate supplier relationship, not none at all.
A narrower relationship, not an exit
The short answer to whether a household can become independent of its energy supplier is that the relationship can be shrunk substantially but not severed. An energy supplier is responsible for providing energy to homes and businesses, and that role persists even for homes that generate1. What changes with generation and storage is the balance of the relationship: less electricity imported, some exported, and payments flowing in both directions.
The clearest evidence of how far this can go is the Feed-in Tariffs scheme. Introduced on 1 April 2010, it was designed by government to promote the uptake of small-scale renewable and low-carbon electricity generation, and it required participating licensed electricity suppliers to make payments on electricity generated or exported by accredited installations6. Over its lifetime the scheme has paid incentives to a cumulative 870,164 small-scale low-carbon installations, which together hold 6.5 GW of generating capacity4. Domestic installations account for the largest proportion of accreditations, at 95.38%, and 45.53% of capacity4. This is generation at household scale, not industrial scale, and it shows the model works.
But the scheme closed to new applications from 1 April 2019, and all pathways for accreditation are now closed2. Closure does not affect installations already accredited, and FIT support is payable for the installation's eligibility period, typically 20 years, with tariffs adjusted annually2. For households installing solar today, the route to being paid for export runs through a supplier's own arrangement rather than a closed national scheme. That is a dependence worth naming: the payment mechanism sits with the supplier, even when the panels on the roof are the household's own.
The Demand Flexibility Service points the same way. Launched in winter 2022/23, it was designed to help manage potential winter pressures by reducing demand during evening peak periods and reducing reliance on more expensive electricity generation7. It exists to make it easier for homes and businesses to take part in the electricity market and be rewarded for shifting when they use electricity7. Participation is a form of engagement with the market, not withdrawal from it, and it typically runs through a supplier or an aggregator.
Statistics: UK reliance and power produced at home
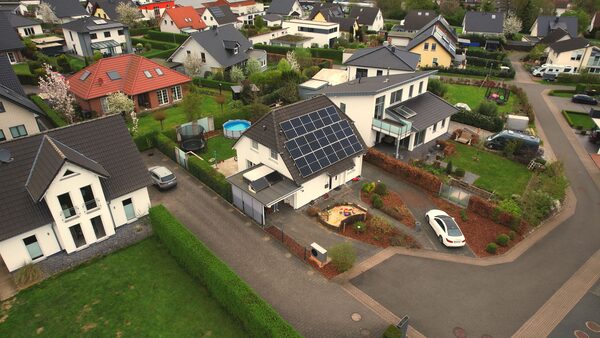
The national picture sets the ceiling on what any household can achieve alone. The UK's fossil fuel dependency, measured as the share of UK energy consumption met by fossil fuels, was 75.2% in 2024, down 1.4 percentage points from 76.6% in 2023, which was itself down from 78.2% in 20223. The direction of travel is downward, but the starting point is high: the UK has been described as a net energy importer with a high dependence on gas and oil8. The Climate Change Committee notes the phase out of coal from UK electricity generation and ongoing expansion of the second largest national offshore wind capacity as markers of change9.
Household generation under the Feed-in Tariffs gives the clearest quantified picture of what homes have contributed. In Scheme Year 14, running 1 April 2023 to 31 March 2024, a total of 8.3 TWh of renewable electricity was generated on the FIT scheme, a decrease of around 0.56 TWh (6.7%) from SY13 levels4. Approximately 1.3 TWh was exported to the grid under the scheme in SY144. The value of the scheme in SY14 was almost £1.86 billion, which included £1.76 billion in generation payments and £78 million in export payments, an increase of £125.3 million (7.3%) compared to SY134.
| Measure | Scheme Year 14 figure |
|---|---|
| Electricity generated | 8.3 TWh4 |
| Electricity exported | approximately 1.3 TWh4 |
| Generation payments | £1.76 billion4 |
| Export payments | £78 million4 |
| Total scheme value | almost £1.86 billion4 |
| Active accreditations | 869,857, a fall of 2064 |
The scale of household participation in flexibility is also now measured. The Demand Flexibility Service incentivised 1.6 million households and businesses in winter 2022/23, saving over 3.3GWh of electricity5. Between December 2024 and March 2025, DFS delivered 3.9GWh of flexibility across 44 events5. Earlier reporting put the reduction delivered throughout events to date at almost 800 megawatt hours, with some companies earning up to £8,0007. The figures differ because they cover different periods and different measures, one being total electricity saved and the other flexibility delivered across counted events.
On the supplier side of the market, the numbers show a market that households can move within. As of September 2016, 14% of domestic consumers received their electricity from suppliers other than the six large energy companies10. The Energy Bills Relief Scheme recorded 101 non-domestic suppliers, an indication of how many licensed entities have operated in the market11. Scottish Government guidance from 2016 noted that the GB energy market leaves two-thirds of households disengaged and paying more for their energy than customers who have switched suppliers12. The gap between what engaged and disengaged households pay is itself an argument for treating the supplier relationship as something to manage actively.
Factors behind the totals
Three forces drive how much of the supplier relationship a household can shed: the price of imported energy, the payment available for generation and export, and the rewards for flexibility.
The first is set largely outside the household. The UK's position as a net energy importer with a high dependence on gas and oil means wholesale prices are subject to volatility that no individual household can control8. The British Energy Security Strategy frames the national response as weaning Britain off expensive fossil fuels, which are subject to volatile gas prices set by international markets, and boosting diverse sources of homegrown energy for greater energy security in the long term13. When Ofgem reviewed the wholesale costs underlying the price cap, it received data from 11 suppliers, reflecting the structure of the market that sets the price most households pay14. Household generation is, in effect, a private hedge against this volatility: every kilowatt hour generated on the roof is one not bought at a price the household does not set.
The second driver is the payment structure for generation. Under the FIT scheme, 99.21% of accredited installations are microgenerators, accounting for 53.78% of installed capacity, while installations above 50kW, just 0.79% of installations, contribute 46.22% of capacity4. In SY14, 14.43% of the total exported electricity was metered, with 85.57% (or 1.13 TWh) deemed4. Deemed export means payment was based on an assumption rather than a measurement, which shaped how much households were paid and how. For new installations outside FIT, export payment terms are set by suppliers, which makes supplier choice a financial decision for generating households, not just a service decision.
The third driver is flexibility. DFS was designed to help manage winter pressures by reducing demand during evening peak periods and reducing reliance on more expensive electricity generation7. From 9 April 2026, changes include a reduced eligibility threshold of 0.1MW, the introduction of bi-directional flexibility, zonal procurement, and a Self-Nominated Baseline option7. From 7 October 2026, DFS will launch the capability to procure constraint management actions, letting participants take part in both margin and system tagged actions7. Each change widens what a flexible home can be paid for, and each payment arrives through a market participant, usually a supplier.
Comparing the two national markets
The UK is not one energy market, and the differences matter for what independence means depending on where a household lives. The Feed-in Tariffs scheme, for example, applied to England, Wales and Scotland, so households in Northern Ireland cannot assume that rules, caps or schemes described for Great Britain apply to them4. Households in Northern Ireland cannot assume that rules, caps or schemes described for Great Britain apply to them, and the separate market is covered in detail on our page about energy suppliers in Northern Ireland.
The Feed-in Tariffs scheme covered renewable and low-carbon electricity generation technologies in England, Wales and Scotland only4. Northern Ireland has its own support arrangements for households generating their own electricity, and nidirect guidance notes that technologies such as solar panels, heat pumps and other energy efficiency measures may offer an attractive payback to homeowners even without grant support15. FIT activity is reported by GB region, including Scotland and Wales, though for some regions micro-CHP, anaerobic digestion and hydro figures are not included in the breakdown due to low numbers of those technologies16. Regionally within the scheme, the South West has the greatest number of installations, 123,256, and the highest proportion of installed capacity, 17.86%4.
Within Great Britain, the supplier market operates as one, but engagement differs. Ofgem's survey of customers' satisfaction with their supplier, covering July to August 2025, found that no suppliers in that survey saw a statistically significant increase in the proportion of customers who said they were satisfied compared to the January 2025 wave17. Satisfaction is not the same as engagement, but a flat picture across suppliers suggests that switching for service reasons matters less than switching for price, and that generation and flexibility are the levers that actually change a household's position.
Scotland's policy framing has long emphasised the cost of disengagement. The Scottish Government's fuel poverty strategy work noted in 2016 that the GB energy market leaves two-thirds of households disengaged and paying more than customers who have switched12. That figure is dated, but the structural point stands across Great Britain: the market rewards attention, and households that generate, store and shift their use are the most attentive participants of all.
Regulations governing switching and assistance
The rules around suppliers determine what a household can and cannot do with its relationship, and several of them work in the household's favour.
Switching itself is protected. Tenants directly responsible for paying the energy bill have the right to switch supplier at any time without incurring an exit fee if they were not informed upfront of the terms and conditions18. This matters for generating households in rented properties: nothing in the switching rules distinguishes a home with solar panels or a heat pump from any other home.
- Special requirements cannot be refused. A supplier is not allowed to refuse your business on the basis that you have special requirements19.
- Supply is protected if a payment plan is kept. All fuel suppliers, electricity and gas, follow a code of practice that means they will not cut off your supply if you agree a payment plan with them and then keep to it20.
- Efficiency funding is not limited to your own supplier. Under the Energy Company Obligation, you can contact any of the obligated energy suppliers to find out how they may be able to help you benefit from the scheme, even if they are not your energy provider21.
- Complaints escalation is free. The Energy Ombudsman is an independent service, separate from Ofgem, for problems with an energy supplier, an energy broker, a network operator, or a heat network supplier, and the service is independent and free for consumers1.
Two rules deserve particular attention from generating households. First, under the FIT scheme, only the owner of the installation or those who have been assigned FIT payment rights may complain or raise a dispute, although non-owners may still make certain information requests22. Second, certain changes must be reported to the FIT licensee: the installation of battery storage with your FIT installation, and the replacing or moving of metering2. Generator obligations under the statement of FIT terms last for the duration of the eligibility period2.
Smart meter data carries its own protections. Suppliers can access daily, or less granular, energy consumption data for any purpose except marketing, with a clear opportunity for the customer to opt out23. For a household using its consumption data to manage generation and flexibility, the rule means the data has value to the supplier as well, and the opt-out is the household's control over that.
On the wider protections, under the Energy Price Guarantee the government sets maximum prices for gas and electricity and compensates energy suppliers for providing energy below those prices24. That scheme, like the price cap, is a GB-wide protection that shapes the ceiling on what a supplier can charge, and it is part of the background against which any household calculates the value of generating its own power.
Self sufficiency in real terms
Taken together, the evidence describes a realistic form of independence: a household that generates, stores, exports and shifts, while remaining connected and paying for the connection.
What can be shed is meaningful. A home with solar panels buys less electricity at prices it does not control. A home with a battery shifts its own generation to the hours it needs it. A home on a flexibility scheme is paid for moving demand away from peak periods, and the national figures show this is not marginal: 1.6 million households and businesses took part in the first DFS winter5. The FIT scheme's scale, 8.3 TWh generated in a single scheme year by mostly domestic installations, shows household generation is a real contributor to supply, not a token one4.
What remains fixed is equally clear, and stating it firmly is part of honest advice.
- The network connection and its charges remain. Standing charges pay for the wires that every home, generating or not, depends on when the sun is down.
- Export payments run through a supplier. The FIT scheme required participating licensed electricity suppliers to make payments on electricity generated or exported6, and post-FIT export arrangements are likewise supplier-mediated.
- FIT accreditation cannot be replaced. The scheme closed to new applications from 1 April 2019, and all pathways for accreditation are now closed2. Existing accredited installations keep their payments for their eligibility period, typically 20 years2.
- Efficiency funding is at suppliers' discretion. Under ECO, it is up to energy suppliers to determine which energy efficiency measures they want to fund, the level of funding they provide, and the retrofit coordinator or installers they choose to work with21.
- The national picture still leans on fossil fuels. At 75.2% of energy consumption in 2024, the system a household is partly independent of is itself still in transition3.
The supplier relationship, in short, changes character rather than disappearing. A generating household is a market participant with leverage: it can switch, it can export, it can be paid for flexibility, and it can escalate to a free ombudsman when things go wrong1. The dependence that remains is on the network, on the payment mechanisms suppliers administer, and on a national system still working off expensive fossil fuels13. Reducing reliance on an energy supplier is a process of narrowing, and the rules, the schemes and the evidence all suggest the narrowing is worth doing deliberately.
Sources24 sources
- Complain about your energy supplier, Ofgem, 2026
- Feed-in Tariffs scheme closure, Ofgem, 2026-09-17
- DESNZ Annual Report and Accounts 2025 to 2026: Performance Report, GOV.UK, 2026
- Feed-in Tariffs Annual Report, Scheme Year 14, Ofgem, 2026-09-17
- Statutory Security of Supply Report 2025, GOV.UK, 2025-12-17
- Feed-in Tariffs Quarterly Report, Issue 63, Ofgem, 2026-03-30
- Demand Flexibility Service, NESO, 2026-09-17
- Spring Statement 2022, GOV.UK, 2022-03
- Progress in Reducing Emissions: 2025 Report to Parliament, Climate Change Committee, 2025-06-25
- Future Insights Series 4, Ofgem, 2017-03
- Energy Bills Support: An Update, National Audit Office, 2024-11-14
- Scotland Without Fuel Poverty: A Fairer Scotland, Four Steps, Scottish Government, 2016-10-24
- British Energy Security Strategy, GOV.UK, 2022-04-07
- Energy Price Cap Wholesale Costs Review, Ofgem, 2023-12-15
- Support to Generate Your Own Electricity, nidirect, 2025-09-22
- Feed-in Tariffs Quarterly Statistics, Ofgem, 2026-09-17
- Customers' Satisfaction with Their Supplier: Supplier Level Findings, July to August 2025, Ofgem, 2025-07
- Tenants' Energy Rights Explained, Ofgem, 2013-09-12
- Consumer Advice: Problems with Services, Anglesey County Council, 2025-10
- Overdue Utility Bills, nidirect, 2026-09-17
- Energy Company Obligation: Homeowners and Tenants, Ofgem, 2026-09-17
- Feed-in Tariffs Dispute Resolution, Ofgem, 2026-09-17
- Final Proposals and Statutory Consultation: Data Privacy, Ofgem, 2014-08-29
- Energy Price Guarantee Research Briefing CBP-9714, UK Parliament, 2026-08-28