
In this answer
Short answer
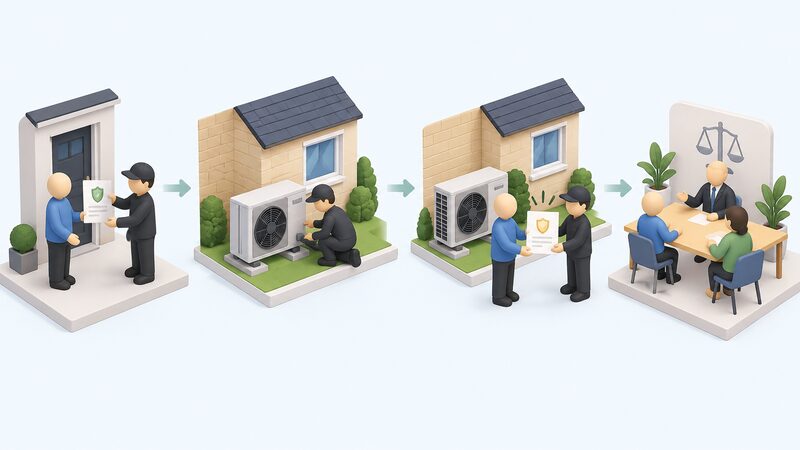
Deposit and stage payment protection is a condition of HIES membership, and it is capped. It covers up to 25% of the contract value, with a maximum of £5,000, and it applies to the deposit and stage payments a household makes before an installation is finished1. Anything paid above 25% of the contract value, up to that £5,000 ceiling, before completion sits outside the protection1.
The cover is not automatic. It is only active once the household receives written confirmation from HIES, and the installer must register the installation with HIES for it to be in place1. Two documents follow: a Customer Registration Certificate and a Deposit and Stage Payment Protection Certificate1.
For a household buying solar panels, a battery or a heat pump, this is the difference between a deposit that is recoverable if the firm stops trading and one that is simply gone. It is a money-protection rule, not a performance guarantee, and it does not remove the household's dependence on the installer's solvency, on the scheme's administration, or on the insurer behind the policy.
What HIES deposit protection is
HIES is a consumer code for home insulation and energy systems work, and it is a TrustMark Scheme Provider4. It is one of only two companies meeting Chartered Trading Standards Institute approved consumer code requirements in the renewables market5. All HIES Accredited Installers operate under a CTSI Approved Consumer Code, and the scheme describes a detailed accreditation process with continuous monitoring to ensure installers meet professional and financial standards2.
The deposit and stage payment protection sits inside that membership. It is not a product a household buys separately from a third party; it is a condition the installer carries as part of being accredited. That matters for how a household should read it. The protection is only as good as the scheme's monitoring and the insurance arrangements behind it, and it depends on the installer having registered the job.
HIES also acts as an alternative dispute resolution provider, so complaints about a member can be escalated through the scheme rather than only through the courts6. For energy independence, the practical value is that a household can commit money to a generating or heating installation without the whole deposit being exposed to one firm's balance sheet. The dependence that remains is on the scheme, the insurer and the installer's continued compliance.
The 2-year deposit protection period: what it covers
The deposit protection period is described as two years by one HIES member, which states that as members of the HIES consumer code it provides 2-year deposit protection3. That figure is a maker's statement about its own membership, not a scheme-wide published term, so it should be read as the period that member advertises rather than a universal rule for every HIES job.
The protection itself covers the deposit and stage payments if the installer stops trading before completing the installation, with completion by another installer or a refund, subject to policy terms1. It is therefore a completion-period protection: it responds to a firm failing mid-job, not to a fault appearing years later.
That is a different job from an insurance-backed guarantee. An IBG is a specialist form of financial protection that can cover a household if the original installer ceases to trade during the guarantee period7, and it protects the homeowner if the installer goes out of business after completing the work, so repairs and workmanship issues can still be addressed8. The two sit at different points in the job.
The periods across the wider market vary. MCS approved financial protection products require at least six years' cover from the moment of installation9, and the maximum period of cover on the insurance-backed guarantee products MCS lists is up to 10 years10. The Installation Assurance Authority offers guarantees for heating measures, heating controls and draught proofing for 2 years11. A household comparing a deposit protection period with a workmanship guarantee period is comparing two different clocks.
| Protection | What it responds to | Period |
|---|---|---|
| HIES deposit and stage payment protection | Installer stops trading before completion | 2-year deposit protection, as stated by one member3 |
| Insurance-backed guarantee | Installer ceases to trade during the guarantee period | Up to 10 years on MCS-listed products10 |
| MCS approved financial protection | Workmanship and completion | At least six years from installation9 |
| IAA guarantees for heating measures and controls | Workmanship or design failure | 2 years11 |
How the protection works if an installer stops trading
If the installer stops trading before completing the installation, the deposit and stage payments can be protected, with completion by another installer or a refund, subject to policy terms1. The household is not left to negotiate with a liquidator; the claim runs through the protection attached to the registered job.
The claim needs evidence. A household provides proof of the payments made to the installer, and the documents required are the contract, all receipts for payments made, and any written guarantees1. Missing receipts are the most common gap, which is why the payment trail matters as much as the certificate.
Where an insurance-backed guarantee is in place, the mechanism is similar in shape. If the installer provides an IBG and then ceases to trade, the insurer will honour the terms of the guarantee issued by the installer, in accordance with the terms and conditions of the policy, and will send qualified tradespeople to assess the issue and arrange remedial work if the claim is valid12. The IAA states that should there ever be a failure in workmanship or design, it will ensure the issue is resolved regardless of the trading status of the installer6.
The limit is the cap. Because cover runs to 25% of the contract value and no more than £5,000, a household that has paid most of a large contract up front has exposed the balance. That is the dependence that remains even with a protected deposit.
What to check before paying a deposit
The first check is whether the installer is a current HIES member and whether the job will be registered. The installation must be registered with HIES by the HIES Accredited installer, and the household should make sure the installation is registered for the protection to be in place1. Written confirmation from HIES is what activates it1.
The second check is the size of the deposit against the cap. Citizens Advice guidance is not to agree to more than 25% on long jobs where a deposit cannot be avoided, and to push it down as much as possible13. That aligns with the protection ceiling, so a deposit at or below 25% is the portion most likely to be covered.
The third check is whether a deposit is needed at all. Deposits are normally only payable where specific or custom ordered items are needed or the installation will take longer to finish14. For a standard installation with off-the-shelf equipment, a large up-front payment is not the norm.
The fourth is the paperwork trail. Keep the contract, every receipt, and any written guarantees, because those are the documents a claim requires1. The Renewable Energy Consumer Code requires its members to protect the money paid in advance of an installation, including the deposit15, so a household can also ask which code the installer belongs to and what that code requires.
- Confirm the installer's current membership and that the job will be registered1.
- Keep the deposit at or below 25% of the contract value13.
- Pay by a traceable method and keep every receipt1.
- Hold the registration and protection certificates once issued1.
- Check whether an insurance-backed guarantee covers the completed work12.
How HIES compares with other consumer protection schemes
HIES and RECC are the two consumer codes relevant to the Boiler Upgrade Scheme, and installers must continue to hold membership with one of the two approved consumer codes to deliver work under that scheme16. Before registering, an investor must be a member of RECC or HIES, both CTSI approved consumer protection codes18. That gives the two codes a formal role in grant-funded work, not just a marketing one.
The schemes overlap in what they offer. Certified schemes such as EVCC and HIES provide assistance in terms of insurance protection and dispute resolution by choosing one of their member installers5. HIES holds an approved product described as a Domestic Property Insurance Backed Guarantee19, and its consumer code is listed with product and workmanship policy coverage20.
Where they differ is in emphasis and in the products listed. RECC requires members to protect money paid in advance, including the deposit15. MCS runs its own financial protection requirements for its redeveloped installer scheme, with approved products carrying at least six years of cover from installation9. The IAA offers guarantees for heating measures, heating controls and draught proofing for 2 years11.
For a household, the practical comparison is not which scheme is better but which protections apply to the specific job. A heat pump installed under the Boiler Upgrade Scheme brings the consumer code requirement with it16. A solar array may bring an MCS-listed insurance-backed guarantee instead. Checking membership is straightforward: EPVS allows a search by installer name to check whether an installer is registered21, and the equivalent route exists for each scheme.
Sources21 cited
- Deposit and Stage Payment Protection, HIES, 2026-07-15
- HIES Homeowners, HIES Scheme, 2026-08-27
- Do Solar Panels Work in a Power Cut, Heatable, 2026-07-13
- About TrustMark, HIES Scheme, 2026-07-15
- Consumer Charter Guide, Flexi-Orb, 2025-02-18
- The IAA Strengthens Consumer Protection, The IAA, 2026-06-17
- Understanding Insurance Backed Guarantees, The CPA, 2025-06-18
- Heat Pump Certifications, The CPA, 2026-04-02
- Robust Financial Protection Is Pivotal to Increasing Confidence in Renewables, MCS, 2026-01-28
- Insurance Backed Guarantee Products, MCS, 2026-05-13
- New Guarantees Available, The IAA, 2026-09-20
- Insurance Backed Guarantees, Flexi-Orb, 2026-02-25
- Before You Get Building Work Done, Citizens Advice, 2026-09-20
- Using a Gas Safe Engineer, Liquid Gas UK, 2026-09-20
- Consumer Leaflet, Renewable Energy Consumer Code, 2026-09-17
- Boiler Upgrade Scheme Guidance for Property Owners, Ofgem, 2026-04-28
- Boiler Upgrade Scheme Guidance for Installers, Ofgem, 2026-04-28
- Domestic Renewable Heat Incentive Annual Report, Scheme Year 11, Ofgem, 2025-07
- MCS Approved Financial Protection Products, MCS, 2026-09-17
- Consumer Protection, EPVS, 2026-09-17
- EPVS Installer Search, EPVS, 2025-07-21
 Deposits and Staged PaymentsHow much deposit should you pay for solar panels or a heat pump, and what happens to your money if the installer goes bust?
 Listed Buildings and AreasYour home is listed or sits in a conservation area, so do you need permission before adding solar panels, insulation or a heat pump?
 When Your Installer Goes BustWhat happens to deposits, part-completed work, workmanship guarantees and complaints when a home energy installation company fails, and how to claim on deposit protection, an insurance-backed guarantee, card or finance cover, and who honours the manufacturer's warranty.
 Comparing Installation QuotesWhat should a solar or heat pump quote actually include before you pay a deposit?
 Installer Schemes and CodesCheck whether your installer is on TrustMark, and whether they belong to HIES or the Renewable Energy Consumer Code.
 Selling a Home With Energy KitCovers the paperwork a sale requires when a home has solar panels, a heat pump, insulation or a leased roof, and how warranties, export payments and guarantees transfer.